You asked the merchant for your money back. They said no, politely, then again. You waited for a third reply that would change nothing, while another clock kept running. The credit card dispute deadline does not care whether the merchant has finished arguing. It started when your statement first showed the charge.
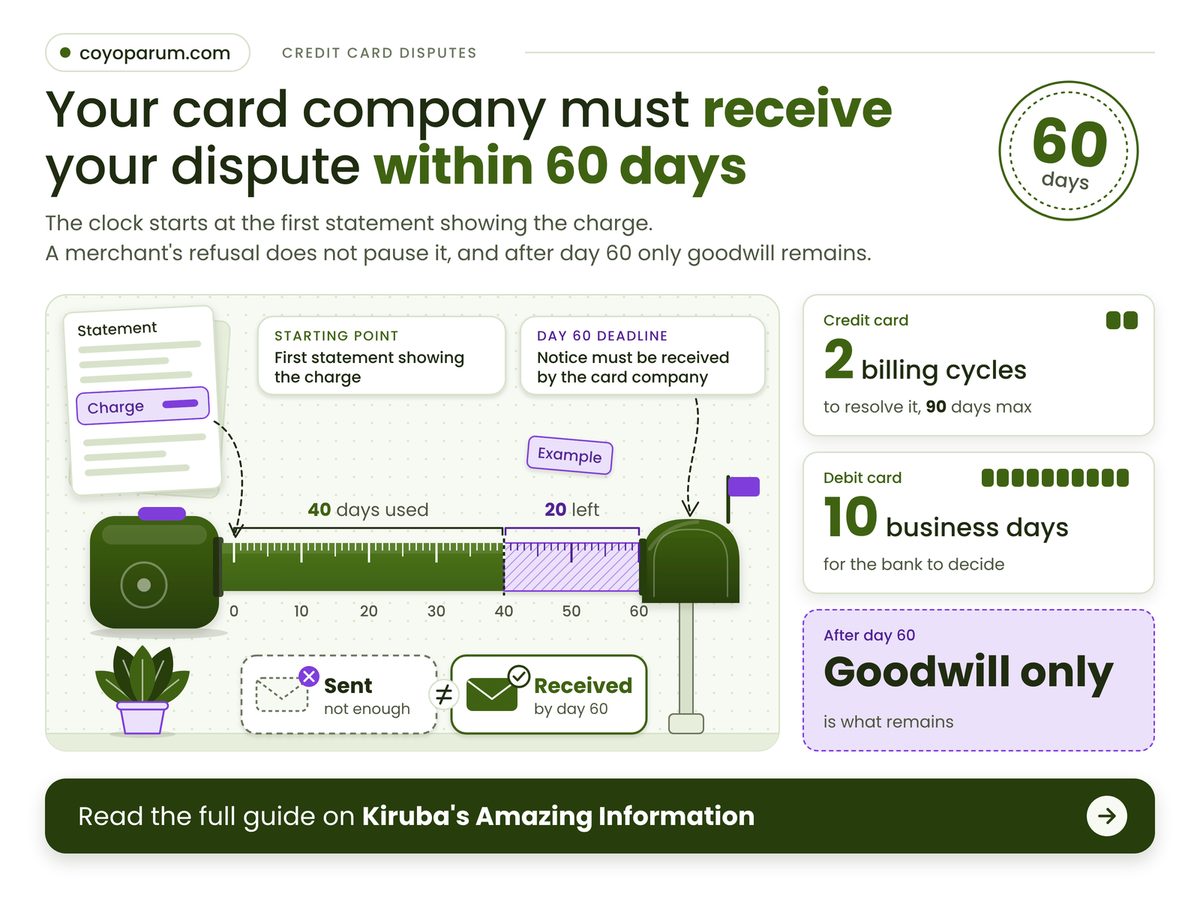
Get a written notice to your card company within 60 days of the first statement showing the charge; a merchant's refusal does not pause that clock.
- Credit: the notice must be received, not sent, and counts from the statement, not the purchase.
- Debit: the same 60 days, a phone call can start it, and the bank has 10 business days to decide.
- Past day 60 the rule stops obliging the bank. File anyway and ask for a goodwill review.
Why does the credit card dispute deadline start at the statement?
Because Regulation Z counts 60 days from when the card company transmitted the first statement showing the charge, not from the purchase, so your clock starts when the bank first shows the charge.
The rule is 12 CFR 1026.13. The CFPB's text says notice must be received "no later than 60 days after the creditor transmitted the first periodic statement that reflects the alleged billing error" (read 9 November 2026). "Received" means a letter posted on day 59 can already be late. "First" means a later statement repeating the charge restarts nothing.
My own arithmetic, not the rule's: assume a 30-day billing cycle. A purchase just before a statement closes shows up on it, leaving about 60 days from payment. One just after waits a cycle to appear, stretching the window to roughly 90. So "I bought it ages ago" means nothing until you find the statement.
The Meta ad refund that support refused after a top-up landed in the wrong ad account and the airline refund rules that survived the 2025 rollback both turn on what a regulator's text, not goodwill, lets you claim.
The FTC's sample dispute letter page, updated June 2026, says to phone first, then write to the billing-error address, by certified mail with return receipt if possible. That address is usually not the payments one. The rule tests receipt, so keep the receipt.
Four figures decide whether a refused refund is recoverable: Regulation Z's notice window and resolution limit, Regulation E's debit deadline, and what one published 2022 refused booking was worth.
Notice Window
60 days
Past it, the rule stops helping
Credit Resolution Limit
2 cycles
Never longer than 90 days
Refused Booking, Reversed
$582
Credited after a CFPB complaint
Debit First Deadline
10 business days
Or provisional credit, then longer
Once a valid notice lands, the issuer owes a written acknowledgment and an answer on a fixed schedule, so your follow-up can name any date it misses. A creditor that fails can face a forfeiture penalty under 15 U.S.C. 1666(e); the CFPB text gives no amount, so treat it as leverage.
A merchant's no is an opinion about your refund. The deadline is arithmetic about a statement, and only one of the two can run out.
Can you dispute a credit card charge after 60 days?
Not as a Regulation Z billing error: past 60 days from the first statement the bank owes you none of that section's deadlines, though it may still choose to look at the charge.
Day counts run from the first statement.
| If you | Do this | Because |
|---|---|---|
| ⏱ Day 45 | Mail a written notice today | It must arrive by day 60 |
| 🧾 Credit, phone | Follow with a written notice | Credit notices must be written |
| 🛠 Debit, phone | Call now, confirm in writing | Bank may ask for writing in 10 business days |
| ⚖️ Merchant said no | Dispute if the goods failed you | Change of mind is no error |
| 🏁 Day 61+ | Send it and ask for goodwill | The rule no longer binds the bank |
Row four is the one people misread. The merchant's reply answers you; the issuer's clock answers to the statement, so a reply on day 50 leaves ten days.
The ring settles whether you still have time: on a statement 40 days old, 20 of the 60 days remain. The 60 is Regulation Z's limit; the 40 is the worked example's assumption.
Worked example: assume a credit card, a first statement transmitted 40 days ago, and a billing-error address four days away by mail. Step one: 60 minus 40 leaves 20 days before the notice must be received. Step two: 20 minus 4 days in the post leaves 16 days to put it in the mail. Result: 16 days to post, on these assumptions. Your own sum takes a minute: take the first statement's date, add 60 days, subtract your letter's travel time.
Does a merchant refusing a refund stop a chargeback?
No, a merchant's refusal neither stops a chargeback nor pauses the 60 days, because the rule ties the clock to the statement, but it must fit a billing error such as goods not delivered as agreed.
A chargeback is the issuer reversing a charge it already paid the merchant (CFPB, September 2024). The request behind it is a billing error notice, and the rule lists what qualifies: an unrecognised charge, a missing credit, or goods or services not accepted or not delivered as agreed.
Our call, and it is opinion: advice to give the merchant one more chance first is out of date once the statement is weeks old. Ask once in writing, and notify the bank the same day. For a subscription that kept billing, the post on what still forces a subscription company to let you quit covers the cancellation side.
One published account, not a pattern: a card holder writing in Motley Fool Money in June 2022 said the issuer closed a refused rental-booking dispute for the merchant after months, having been told photos and video were not used. A CFPB complaint then won the full amount. The lesson: ask the issuer in writing what evidence it accepts. I could not confirm current CFPB response times.
Watch for these:
- Debit costs cash while you wait. The debit card dispute deadline for you is 60 days; the bank has 10 business days, up to 45 with provisional credit, and 90 for point-of-sale debit (12 CFR 1005.11).
- A chargeback time limit near 120 days is often reported; I could not source it, so do not plan around it.
Check these about your own charge before you send
- The statement that first showed the charge is under 60 days old.
- The charge is unrecognised, undelivered or not as agreed, rather than a change of mind.
- You have the billing-error address from the statement, not the payments address.
- If it is a debit card, you can phone the bank today.
This week: find the statement that first showed the charge, add 60 days, subtract your letter's travel time, and send a written notice by tracked mail to the billing-error address before then, using the FTC's sample letter. If the date has passed, send it anyway and ask for a goodwill review. This is wrong for a change of mind, so first check your charge matches a listed error. Not legal advice.
How we checked this
We read the CFPB's text of 12 CFR 1026.13 and 12 CFR 1005.11, and its refund page (modified 6 September 2024), on 9 November 2026. The worked example assumes a credit card, a 40-day-old statement and four days of mail. No product was tested hands-on for this article, and no dispute was filed. Last verified: 9 November 2026.
Edited by Kiruba, reviewed after publication. Spotted something out of date? Tell us and we will correct it.